Why Now Is The Time To Buy Sydney Metro Office
Acure Asset Management provides in-house research, analysis and news bulletins to subscribers on a monthly basis.
Our reports are based on Australian Property and Market trends as they happen – as well as reflective reports on our portfolio and performance.
Subscribe for more tailored News and Insights from Acure Asset Management below or on our Contact page
Chatswood and St Leonards are at the point in the office cycle where patient capital is rewarded: leasing demand has turned positive, incentives look to have peaked, and almost no new office space is coming.
Two years after Sydney Metro City & Southwest opened, both precincts sit four minutes apart on a line that reaches Barangaroo and Martin Place in under a quarter of an hour. Yet prime yields of around 8.1% price them roughly 245 basis points wide of the Sydney CBD.
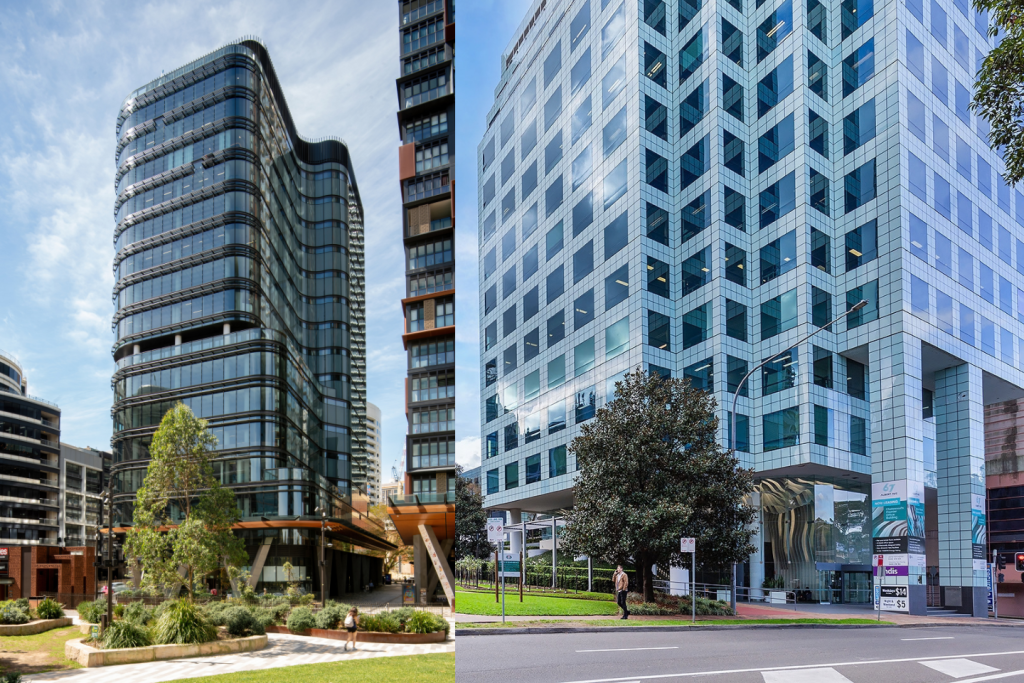
That combination of recovering occupier demand, a shrinking supply pipeline and step-change connectivity, bought at cyclically soft pricing, is why we believe now is the time to own quality office in these markets. Two A-grade assets illustrate the opportunity: 67 Albert Avenue, Chatswood and 558 Pacific Highway, St Leonards.
Fundamentals are Turning
Occupier demand has swung back to positive. In the second half of 2025, and first half of 2026 Chatswood, Crows Nest/St Leonards and North Sydney all recorded positive net absorption at the same time for the first time since H1 2018, and the North Shore’s combined 8,030 sqm was its strongest six months since H2 2020.
St Leonards is leading the turn. It was the only North Shore market to record positive net absorption across calendar 2025, taking total vacancy from 30.5% to 29.1% and prime vacancy from 26.1% to 23.4% (Knight Frank). Vacancy fell again in the first half of 2026, to 27.7% (Knight Frank Q2 2026), and the Property Council named Crows Nest/St Leonards among the few markets nationally to tighten (PCA via CRE).
Chatswood remains Sydney’s tightest suburban market. Vacancy fell from 20.2% to 18.5% over H2 2025, with prime vacancy down from 31.0% to 28.3%. It ticked back up to 19.4% in July 2026, but still sits below North Sydney (24.9%), Macquarie Park (25.1%) and Parramatta (23.0%).
Both Chatswood and St Leonards vacancy totals are being skewed by older, B and C-Grade office stock (such as 475 Victoria Avenue and 9 Help Street) – some of which is ear marked for withdrawal or conversion to residential, and has current vacancy levels of up to 50%.
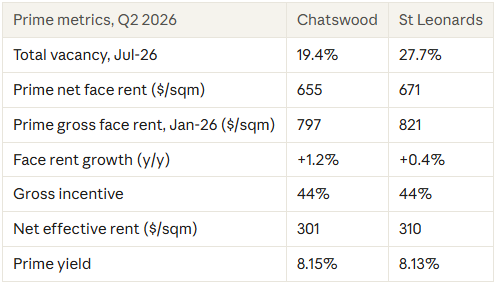
Face rents are holding; incentives are the swing factor. Gross face rents of around $800/sqm have held or edged up, but incentives climbed from 38% in January 2025 to 44% by mid-2026, pushing net effective rents down 7–8% over the year. Knight Frank’s view is that incentives have now topped out and effective rents will return to growth as enquiry improves.
That is the opportunity. Buying when incentives are at a cyclical peak means acquiring income at trough effective rents. As vacancy tightens and incentives unwind, even flat face rents translate into effective rental growth, the pattern now playing out in the Sydney CBD, where net effective rents rose 12.2% over the year to Q2 2026.
A Supply Drought, and Stock Leaving the Market
Virtually no new office space is coming to either precinct, and in St Leonards existing office is being taken out of the market for housing.
The national picture sets the scene. Just 176,303 sqm of office space was completed across Australia in the first half of 2026, the lowest since July 2017, and even less is expected in the second half. Knight Frank notes economic rents remain well above achievable market rents, making new towers largely unviable and concentrating demand into existing buildings.
Chatswood: the commercial core has not seen a new office building since the Zenith in the mid-1990s, and Knight Frank reports no new office developments scheduled for delivery over the next couple of years. Every square metre of future demand must be met from existing stock.
St Leonards: the pipeline is going backwards. Stockland has lodged plans to replace its approved 42-storey office tower at 601 Pacific Highway, which would have delivered more than 56,000 sqm of office space, with a 52-storey, 538-apartment residential tower, demolishing the existing 14-storey office building in the process. Aqualand is pursuing a 49-storey residential tower at 33–37 Herbert Street. The only notable commercial addition is about 8,000 sqm in Deicorp’s Five Ways mixed-use project at Crows Nest.
Metro has Redrawn the Map
Sydney Metro has turned Chatswood and St Leonards from suburban satellites into stops on the CBD’s fastest rail spine. The City & Southwest section opened on 19 August 2024, extending the line from Chatswood under the harbour through Barangaroo, Martin Place and Central to Sydenham, with a train every four minutes in the peak.
For occupiers, that matters in three ways:
Talent reach. A single seat now links the North Shore, Macquarie Park and the Hills with the CBD and the south-west, widening the commutable workforce for a North Shore office.
A credible CBD alternative. A business can sit four to five stops from Barangaroo while paying around half the CBD’s $1,470/sqm prime net face rent.
Flight to connected quality. Knight Frank expects the Crows Nest station to encourage tenants in secondary St Leonards buildings to upgrade into better-located prime space, the segment where vacancy is already falling fastest.
North Sydney shows the pattern: Knight Frank credits Metro and Victoria Cross Station with underpinning its long-term appeal to occupiers. Chatswood and St Leonards offer the same connectivity at a lower rent and a higher yield.
Why the Window is Now
Pricing has already reset; the fundamentals are only beginning to follow. Chatswood core yields have moved from 5.25–6.25% in mid-2019 to 7.50–8.50% today, and prime yields of 8.1–8.2% in both precincts sit about 245 basis points above the Sydney CBD’s 5.70%.
Capital is starting to notice. North Shore office sales reached $927 million in 2025, Investa and BGO paid $558 million for 100 Mount Street in North Sydney, and 9 Help Street, Chatswood traded for $90 million in Q2 2026. Knight Frank expects interest rates to trend lower around late 2027–2028, a further tailwind for yields.
The recovery is not complete. Vacancy remains elevated, incentives are high and Chatswood’s vacancy rose in the first half of 2026. But those are the conditions that create entry points. Investors who wait for falling incentives and rising effective rents to show up in the data will likely be paying tighter yields to buy the same buildings.
Positive absorption, a pipeline that is shrinking rather than growing, and Metro connectivity that is here today point the same way: well-located, A-grade office in Chatswood and St Leonards is being priced at the bottom of the cycle.
The Opportunity: Sydney Metro Office Trust
The Sydney Metro Office Trust is seeking to raise $183 million to acquire two exceptionally presented A-grade office towers, strategically positioned across Sydney’s premier non-CBD commercial precincts.
The Portfolio provides immediate scale within two of Australia’s highest performing metropolitan office markets, purchased at a blended average yield of 9.5% (on a fully leased basis) and with a portfolio WALE (weighted average lease expiry) of 3.95 years (by income), the investment represents an exciting value acquisition of the best office asset in each respective precinct.
Key Opportunity Highlights:
Initial (year 1) Distribution Yield: 9.2%
Forecast 5yr Average Distribution Yield: 8.5% p.a.
Target Total Return (IRR) after all fees and costs: 14% p.a.
74% tax deferral on distributions forecast for the first 3 years
To request a copy of the Information Memorandum, invest, or speak to a member of Acure’s Distribution team, use the buttons below:
– James Del Borrello [email protected]